Do You Need to Register with HMRC as a Tax Adviser? Here's What We Know
Discover HMRC's first agent registration guidance, covering key deadlines, registration conditions, and professional body concerns for HMRC Agent Registration.

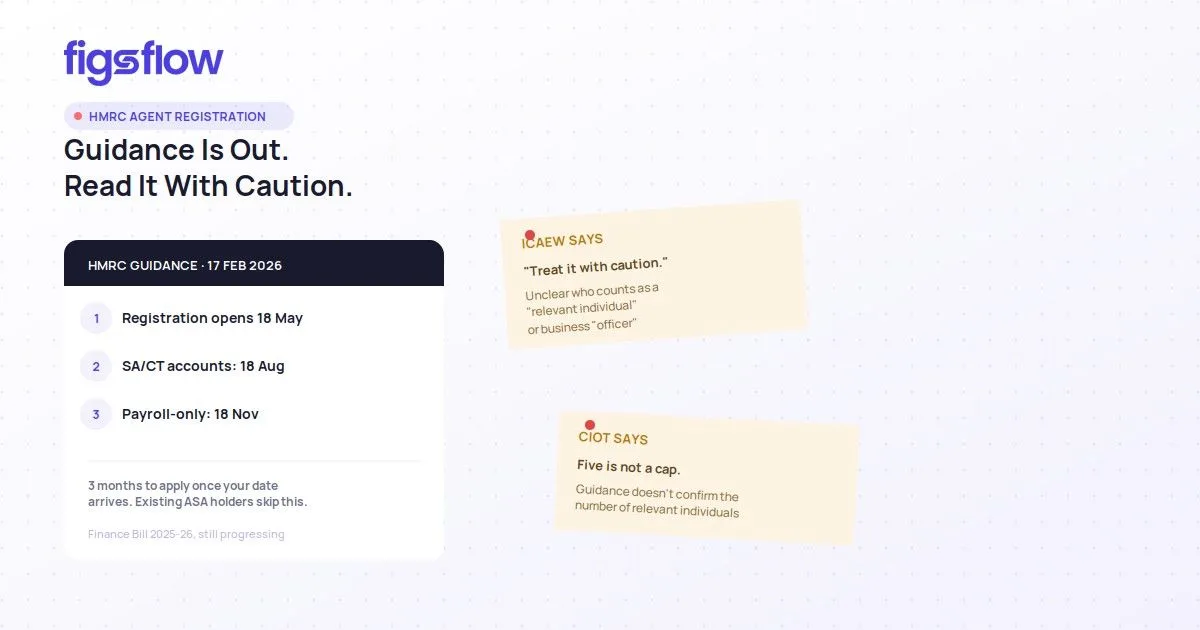
HMRC has published its first official guidance on mandatory agent registration, setting out who needs to register, when, and what conditions apply.
The guidance went live on 17 February 2026 and marks the beginning of a significant change to how tax advisers interact with HMRC on behalf of their clients.
Understanding HMRC Agent Registration Requirements
The new guidance sits within the Finance Bill 2025 to 26 and introduces a legal requirement for many tax advisers to register with HMRC.
From 18 May 2026, a new online registration system will replace the current process for obtaining an Agent Services Account. If you already have an Agent Services Account, you do not need to register again. HMRC will contact you through your existing account when it needs to verify that you meet the registration conditions. See our full guide on tax adviser registration with HMRC for what has changed and what you need to do.
Who Needs to Register
If your business interacts with HMRC about someone else’s tax affairs and gets paid for it, you are required to register. This applies even if you do not describe your work as tax advice, work as a sole trader, only act for one client, or are based outside the UK. The legal entity that interacts with HMRC must register, not individual employees.
Some businesses are exempt. You will not need to register if you:
- run payroll for your own staff,
- deal only with tax matters within your own company group,
- provide tax advice for free, or
- supply payroll and accounting software without directly interacting with HMRC.
You can check the full list of exempitons in HMRC’s guidance on meeting the registration requirements.
Key Dates for Registration
Here is when you need to register, depending on your situation:
- 18 May 2026 Registration opens. Advisers with no Agent Services Account, Self Assessment account, or Corporation Tax account must register by 18 August 2026.
- 18 August 2026 Registration opens for advisers who have an existing Self Assessment or Corporation Tax account but no Agent Services Account. Deadline to register: 18 November 2026.
- 18 November 2026 Registration opens for agents who only provide third-party payroll services. Deadline to register: 18 February 2027.
- 31 December 2026 Registration opens for advisers who already hold an Agent Services Account and for financial services organisations. Deadline to register: 31 March 2027.
In all cases, you have three months from your required registration date to apply, and you can continue to interact with HMRC on behalf of clients throughout that period.
What the Professional Bodies Are Saying
Both CIOT and ICAEW have raised concerns about the guidance despite welcoming its publication.
ICAEW has advised tax advisers to treat it with caution, noting that it oversimplifies the legislation in places. Specific concerns include an inaccurate description of who counts as a relevant individual, insufficient detail on what makes someone an officer of a business, and a lack of clarity on whether family offices need to register.
CIOT separately flagged that the guidance does not make clear that the number of relevant individuals is not capped at five, and has spoken to HMRC about updating this.
Both bodies recommend reading the guidance alongside the relevant clauses of the Finance Bill before drawing any firm conclusions about your registration obligations.
What Happens Next
HMRC has confirmed it will update the guidance before the May 2026 registration window opens, including full instructions on how to register. The Finance Bill 2025 to 26 is still progressing through Parliament, so further changes to the detail remain possible. CIOT and ICAEW are both engaging with HMRC to push for clearer guidance, particularly around relevant individuals and group registration questions.
Advisers should watch for updates through their professional body and through HMRC’s agent services communications over the coming months.
Run your firm on one platform
Proposals, engagement letters, pricing and AML — built for ACCA, ICAEW, ATT, CIOT, AAT and CIMA firms.